
Tools to Correct Self-Deception
I used to wonder how my clients got so good at deceiving themselves.
They would tell me what they wanted, then make choices that took them somewhere else.
They would say “I want to accelerate my retirement,” but then stretch to buy a vacation home.
They would tell me “I can’t stomach portfolio losses,” but then make speculative bets on a whim. Despite articulating rational objectives in the planning process, the subsequent decisions and actions were not aligned. It’s quite common and seemingly illogical.
Then I discovered how good I am at deceiving myself.
Once I understood how natural and normal it is to develop blind spots, it changed the way I approached financial planning. It led to me to the principles and tools discussed below.
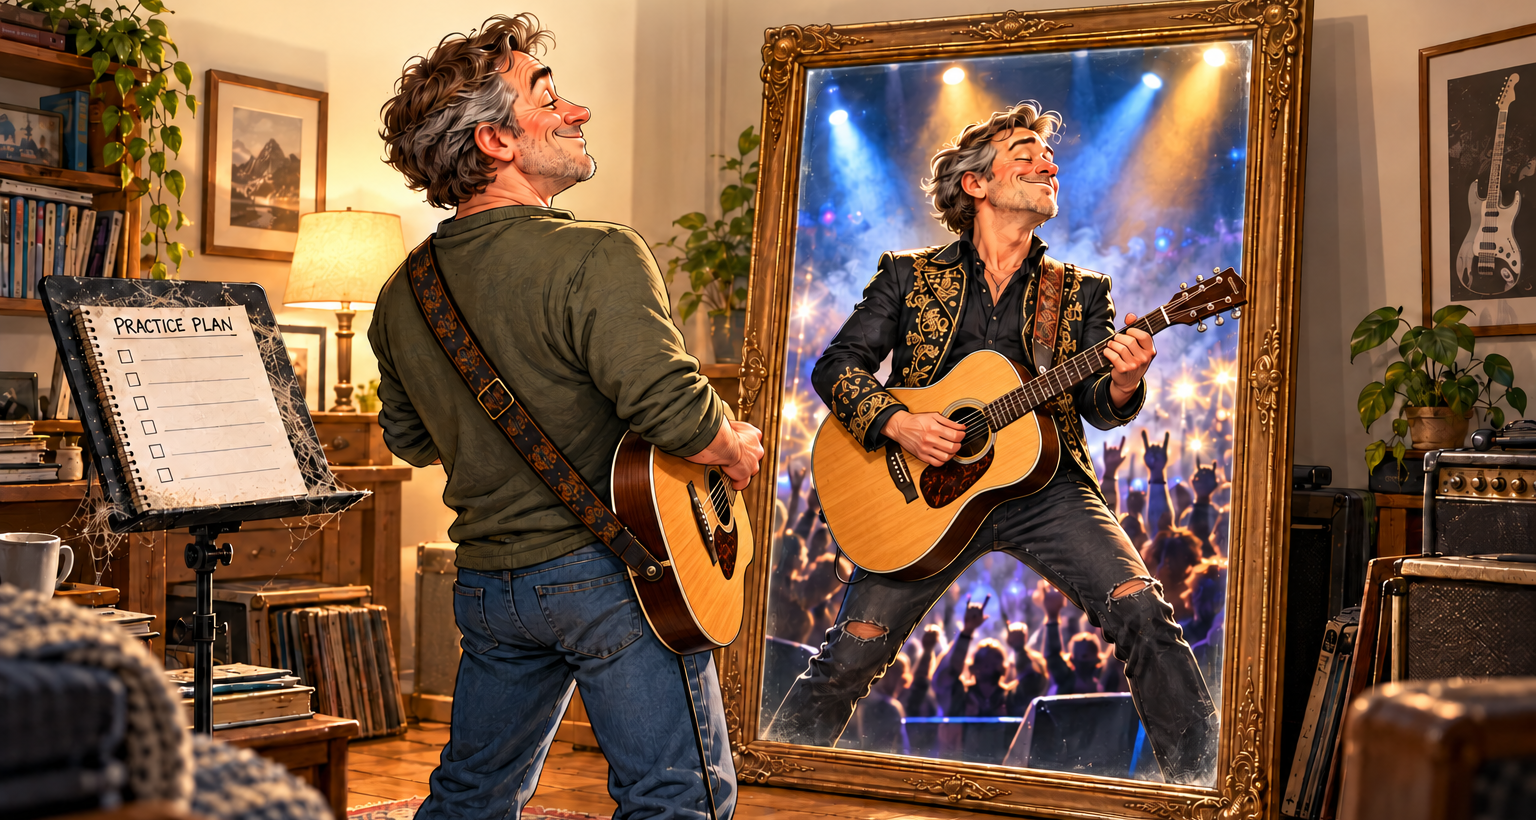
My guitar playing illustrates this idea of self-deception and blind spots. I love playing even though I am a 4-chord hack. Every time I pull out that beautiful acoustic Martin, I fall in love again with the idea of becoming good. I routinely commit in my mind to practice, exercises, learning theory and drilling scales. Often, I “commit” by buying another online subscription (Learn to be a Blues Master in 30 Days!). Despite the repeating pattern of enthusiastic promises, I have been playing the same 20 songs at the same level for years.
“I want to get better” is easy to say, and genuine. The deception is that I am so motivated to get better that I will give up hours of weekly free time to do drills. The deception is that with some simple routine discipline I could blossom into a respectable guitarist. Occasionally I would daydream about being good enough to perform live. But the reality is, in the full context of my life, my priorities, restraints, and limitations, mastering the guitar was not something I was willing to pursue.
The cold truth is that I am in fact satisfied and fulfilled by my current level of playing. When I proactively and thoughtfully consider my priorities and available time, I quite rationally don’t choose “dedicate 8 hours a week to guitar.” Admitting that truth turns off that nagging internal dialog that says “you should really practice more” and just lets me enjoy and appreciate my four-chord reality (apologies to my family who will forever hear simplistic versions of Hotel California and Country Roads).
The deceptions I encounter in client meetings are similar. They are more like blind spots than intentional lies. All of us accumulate financial mental clutter. These ideas are like those beloved 30-year-old jeans taking up space in the drawer—they fit a version of us that no longer exists and we can’t admit it. Sometimes they are oft repeated remnants of someone else’s version of success or arbitrary standards that have become irrelevant. The blind spots grow as a consequence of personal evolution, changing income, bigger responsibilities, maturing, growing complexities and, ironically, gaining wisdom.
I have learned to recognize the clues. When actions and decisions don’t align with stated objectives (my clients or my own), I know there is a need for some soul searching and closet cleaning. Accountability follows honesty. The guitar serves as a useful metaphor, but when it comes to self-deception in our financial lives, we should pay attention.
When the stakes get higher
Consider a familiar financial planning situation. Five years ago, a client might have told me she needed $4 million to retire. That portfolio would mean she could, with great satisfaction, quit the employer that underappreciates and underpays. She could payoff the house, spend time with family, play tennis, and travel. Today, that same client has an $8 million portfolio boosted by rising markets and a seven-figure position in the company stock she accumulated through RSU grants. Her net worth is two times the original target and carrying significant concentration risk.
Considering the original goals, the actions and next steps seem obvious. But she hesitates to sell stock and once again says she will wait for the next vesting period to think about retiring. This is what looks to me like self-deception brought on by a lot of change. Those goals were set when $4 million felt like a stretch, her lifestyle was more modest, she had a different title at work, and her company stock was $200 per share lower.
We need to explore. Maybe her ambitions expanded—a better country club and first-class travel now feel like necessities. The tradeoffs of office politics are now worth it. Maybe after seeing others retire, the thought of not being needed at the office is unappealing. Maybe she hasn’t taken the time to consider the downside risk of the concentrated position, or, maybe she has but is hesitant to say out loud she is willing to roll the dice for the prospect of further gains.
My goal as a planner when I see this is to get the truth said out loud, acknowledge the change, restate the goals, assess the risks, empower the client to make decisions and ultimately to act on them. “I think the stock will go higher” is not enough. We need to push to: “I think this money will allow me to fund my retirement and set my kids up. I believe the potential additional gain in the company stock is worth the risk of holding, so I want to hold all of it until next April or until it crosses $500 per share”. At that point, we have cleaned out the clutter of old ideas and illuminated the blind spots.
These discrepancies are ordinary features of being human. We change. We discover competing desires. We avoid difficult decisions. Our habits outlive the intentions that created them. But money touches our security, our families, our freedom, and much of what we hope to experience. Leaving those discrepancies unexamined can become expensive—in dollars and in years.
We need principles for examining them and tools for acting on what we discover.
Examine the setting
The practice of questioning our professed beliefs reaches back to Socrates. In Plato’s dialogues, he asks people to explain their convictions and examines whether their answers hold together. The interrogation reveals how often there are big problematic gaps.
We can apply that spirit to our own choices: I say this matters. I act this way. How do I reconcile the two?
Chris Argyris thought a lot about that and offers “Double Loop Learning” as a tool. In his 1977 Harvard Business Review article, “Double Loop Learning in Organizations,” he uses a thermostat to explain two kinds of learning. A thermostat set to 68 degrees detects a colder room and turns on the heat. It corrects the discrepancy while keeping the target intact. That is single-loop learning.
A thermostat capable of examining whether 68 degrees is the right setting would be engaging in double-loop learning. It questions the target and the assumptions governing its response. His framework concerns organizations; here, we are applying it to personal financial decisions.
Single-loop learning asks: What must I change to reach this goal? Double-loop learning adds: Does this goal still make sense, and what assumptions am I relying on?
When it comes to financial planning, we have a tool and process that provides clarity and enables double loop learning.
The Monthly Reckoning
For financial matters, one of the most useful tools is a pro forma cash flow: a forward-looking plan for the money you expect to receive and how you intend to use it.
The name sounds more imposing than the exercise. Start with next month’s income. Account for taxes, obligations, and ordinary expenses. Then identify what remains available and decide what it will serve. Extend the forecast through the next year so annual expenses and larger plans have a place.
Suppose you have $5,000 a month available. How much goes toward financial independence? Travel? Giving? Paying down debt? Helping your children? How much stays available for unplanned enjoyment? You may decide to cut the vacation budget because an earlier retirement matters more. You may double it because traveling together while you are healthy matters more.
Sounds like budgeting, but budgeting is single loop learning like the thermostat. Forward looking cash flow planning is double loop learning, illuminating the limitations or excesses of your current situation and forcing you to adapt and update. Where will the money come from? What will you give up? What happens to the other goals? A desire becomes a commitment when you assign it resources and accept the tradeoff.
This is a monthly confrontation with reality in a spreadsheet. I do a quick version weekly and spend about two hours a month on it personally. I encourage every client to do it. This one habit keeps the financial clutter to a minimum, keep goals on track, and illuminates the blind spots.
Socrates famously said, “The unexamined life is not worth living.” That examination helps us discover whether what we say we want is still what we want—and whether our choices are moving us toward it.
Sources
Plato, Apology, especially 21b–23b and 38a; translated by Benjamin Jowett.
Editorial note: The financial scenarios are illustrative.


